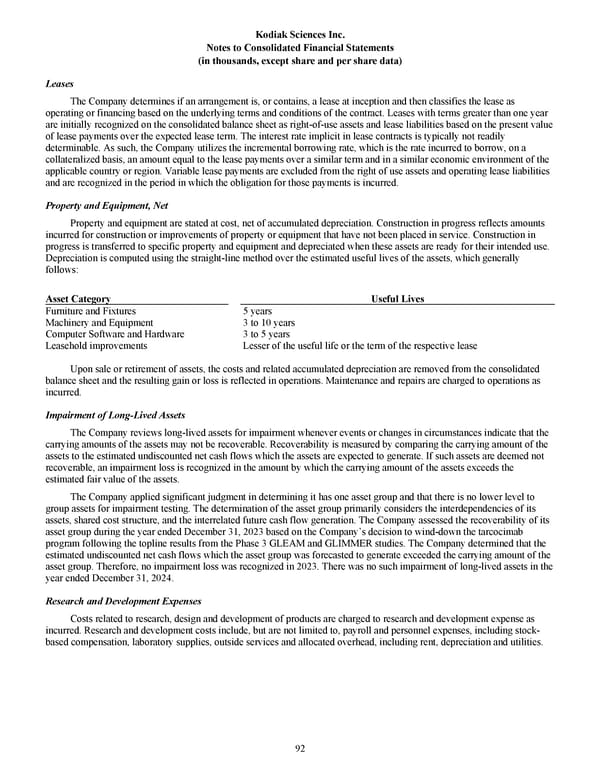
Kodiak Sciences Inc. Notes to Consolidated Financial Statements (in thousands, except share and per share data) 92 Leases The Company determines if an arrangement is, or contains, a lease at inception and then classifies the lease as operating or financing based on the underlying terms and conditions of the contract. Leases with terms greater than one year are initially recognized on the consolidated balance sheet as right-of-use assets and lease liabilities based on the present value of lease payments over the expected lease term. The interest rate implicit in lease contracts is typically not readily determinable. As such, the Company utilizes the incremental borrowing rate, which is the rate incurred to borrow, on a collateralized basis, an amount equal to the lease payments over a similar term and in a similar economic environment of the applicable country or region. Variable lease payments are excluded from the right of use assets and operating lease liabilities and are recognized in the period in which the obligation for those payments is incurred. Property and Equipment, Net Property and equipment are stated at cost, net of accumulated depreciation. Construction in progress reflects amounts incurred for construction or improvements of property or equipment that have not been placed in service. Construction in progress is transferred to specific property and equipment and depreciated when these assets are ready for their intended use. Depreciation is computed using the straight-line method over the estimated useful lives of the assets, which generally follows: Asset Category Useful Lives Furniture and Fixtures 5 years Machinery and Equipment 3 to 10 years Computer Software and Hardware 3 to 5 years Leasehold improvements Lesser of the useful life or the term of the respective lease Upon sale or retirement of assets, the costs and related accumulated depreciation are removed from the consolidated balance sheet and the resulting gain or loss is reflected in operations. Maintenance and repairs are charged to operations as incurred. Impairment of Long-Lived Assets The Company reviews long-lived assets for impairment whenever events or changes in circumstances indicate that the carrying amounts of the assets may not be recoverable. Recoverability is measured by comparing the carrying amount of the assets to the estimated undiscounted net cash flows which the assets are expected to generate. If such assets are deemed not recoverable, an impairment loss is recognized in the amount by which the carrying amount of the assets exceeds the estimated fair value of the assets. The Company applied significant judgment in determining it has one asset group and that there is no lower level to group assets for impairment testing. The determination of the asset group primarily considers the interdependencies of its assets, shared cost structure, and the interrelated future cash flow generation. The Company assessed the recoverability of its asset group during the year ended December 31, 2023 based on the Company’s decision to wind-down the tarcocimab program following the topline results from the Phase 3 GLEAM and GLIMMER studies. The Company determined that the estimated undiscounted net cash flows which the asset group was forecasted to generate exceeded the carrying amount of the asset group. Therefore, no impairment loss was recognized in 2023. There was no such impairment of long-lived assets in the year ended December 31, 2024. Research and Development Expenses Costs related to research, design and development of products are charged to research and development expense as incurred. Research and development costs include, but are not limited to, payroll and personnel expenses, including stock- based compensation, laboratory supplies, outside services and allocated overhead, including rent, depreciation and utilities.
 Kodiak Sciences 2024 Annual Report Page 103 Page 105